* Money Manager Z·X·N – Global Accepting!
* Account Entrusted Investment, Activate with Authorization!
* Institutions | Investment Banks | Funds | Offshore Wealth | Family Offices
* MAM | PAMM | LAMM | POA | Joint Accounts.
* Minimum investment is $500,000; verify returns before entrusting.
* 50% Profit Share | 25% Loss Participation.
* 20%+ Sustained Annualized Returns | Multi-Year Trade & Position History Available for Verification.
All the problems in forex short-term trading,
Have answers here!
All the troubles in forex long-term investment,
Have echoes here!
All the psychological doubts in forex investment,
Have empathy here!
Within the two-way trading structure of foreign exchange (forex) investment, fund managers must exercise prudence in selecting high-quality account principals.
The forex market differs fundamentally from traditional one-way markets; its core characteristics include a two-way trading mechanism, the magnifying effect of leverage, and continuous, round-the-clock price volatility. While the ability to open both long and short positions offers a broader range of trading opportunities, it also significantly amplifies the volatility of an account’s net value. There is a marked disparity in risk tolerance and the likelihood of potential disputes depending on the size of the capital in an account.
When fund managers take on managed accounts, smaller accounts present higher risks—both in terms of regulatory compliance and practical execution. Due to the use of leverage, two-way trading can lead to rapid drawdowns in net value or a sharp expansion of floating losses, especially during periods of intense short-term market turbulence or sudden reversals in direction. For many small-scale investors, the capital deployed represents their entire investable wealth; consequently, their risk threshold is low, making it difficult for them to objectively accept the routine fluctuations in profit and loss inherent to two-way trading. Such principals often lack the psychological capacity to tolerate losses. Furthermore, their decision to entrust funds is frequently not driven by a genuine need for professional asset management, but rather by a desire to observe the fund manager’s trading strategies—meaning they lack any real intent for a long-term professional engagement.
In contrast, high-net-worth or affluent clients typically view their trading capital as only one component of their broader asset allocation. They generally possess a more mature understanding of risk and a greater tolerance for the ups and downs of trading. When faced with standard market scenarios—such as shifting between long and short positions or market reversals—these clients tend to remain composed, rarely giving rise to operational disputes or conflicts. Established fund managers in the industry often set a minimum threshold for managed capital—frequently in the range of one million currency units—primarily to ensure that the clients they accept have the genuine capacity to bear the associated risks.
In summary, within the context of leveraged, two-way foreign exchange (forex) trading, fund managers should strengthen risk controls at the front end of their operations. This includes establishing clear client onboarding criteria, accurately assessing investors' understanding of risk, and explicitly defining the rights and obligations of both parties at the outset of the partnership. Such measures help effectively mitigate potential conflicts and legal or compliance risks during the course of actual trading.
In the T+0, two-way trading environment of the forex margin market, it has become industry standard for traders to disclose their actual account statements.
These performance disclosures are based on real account transaction records, covering long and short positions as well as gains and losses across various timeframes. They are authentic and legally valid—by no means do they constitute false advertising. However, given the high volatility and shifting trends inherent in the forex market, past performance merely reflects the effectiveness of a strategy during a specific period; it cannot guarantee future returns. This is a standard, inherent risk of the market.
In legal or commercial disputes, clients sometimes allege that prior performance disclosures were "false advertising" simply because their accounts experienced a drawdown. Such claims lack a sound legal basis. False advertising fundamentally involves the fabrication or tampering of data—practices that do not apply to the disclosure of genuine performance records. Subsequent gains or losses are influenced by a multitude of variables, such as the release of macroeconomic data, shifts in market liquidity, and the alignment of strategy parameters; these are considered normal commercial risks and risks inherent to trading itself.
Therefore, the disclosure of performance based on authentic data by a fund manager is both compliant and legal. Clients must understand that forex trading is, by nature, a game of probabilities rather than a promise of certainty. Investors are expected to bear the risks of market volatility themselves and cannot use subsequent financial outcomes as grounds to claim that prior performance disclosures were fraudulent or non-compliant.
In the practice of foreign exchange and futures investment, fund managers are frequently asked during business negotiations—prior to formal engagement—to provide "preliminary two-way trial trades." This serves as a foundational trust-building exercise, intended to verify the manager’s strategic logic, risk management capabilities, and proficiency in analyzing both long and short market positions.
However, this seemingly routine business development tactic actually harbors significant legal risks—a "compliance blind spot" frequently overlooked by many practitioners.
Foreign exchange and futures markets are characterized by high leverage, T+0 settlement, and the ability to trade in both directions, all within a highly volatile environment. If a fund manager lacks the proper investment advisory credentials yet provides specific trading instructions, price points, or strategic assessments to a client, such actions may easily be classified as "illegal investment advisory services." In the context of trial trades, in particular, should a client follow the manager’s long/short strategy with real capital and subsequently incur losses, the manager could face severe civil liability for damages.
To strike a balance between business development and regulatory compliance, fund managers must strictly implement the following risk control measures:
First, a robust disclaimer mechanism must be established. When presenting trial trade records or simulated trading results, it must be explicitly stated that the content serves solely as an "illustration of trading concepts" or "reference for long/short strategies." It should be clearly declared that such information does not constitute a formal offer to trade or operational guidance; clients must be strictly prohibited from directly replicating these trades, and it must be emphasized that the client bears full responsibility for any resulting gains or losses.
Second, it is essential to maintain the "non-remunerated" nature of the service. During the preliminary trial phase, the service must remain strictly non-commercial in character. Providing such reference-only information without charge is generally not classified as an illegal commercial investment advisory activity, thereby effectively mitigating the risk of administrative penalties.
In summary, while "trial" trades—executed via the two-way (long/short) capabilities of forex futures—can serve as a supplementary tool during business negotiations, fund managers must strictly adhere to compliance requirements. This includes implementing robust risk disclosures and liability disclaimers, ensuring that while professional expertise is demonstrated, legal risks and potential claims for damages are effectively mitigated.
In the context of two-way forex trading, does a fund manager’s claim of "long-term profitability" constitute false advertising? This is a classic compliance issue within the realm of third-party forex asset management, and its classification depends on both the specific content of the claims and the inherent characteristics of the forex market.
The forex market differs fundamentally from the one-way trading typical of stock markets. Its core attributes include two-way tradability (the ability to open both long and short positions), a "T+0" settlement mechanism (immediate liquidity), and high-frequency exchange rate volatility. When managing funds on behalf of clients, many forex fund managers promote their past trading performance; the compliance boundaries surrounding such promotional language represent a frequent area of risk in both industry regulation and judicial practice.
In practice, forex fund managers often cite their own historical trading data to claim "long-term profitability." This type of statement occupies a distinct "gray area" in terms of compliance. The underlying logic is as follows: two-way forex trading is influenced by a complex array of variables—including bidirectional exchange rate fluctuations, leverage-related exposure, sudden market events, and the duration of held positions. Consequently, historical long-term profitability cannot be equated to short-term performance or future outcomes, nor does it serve as an indicator of subsequent returns. In two-way forex trading, every position—regardless of direction—carries inherent uncertainty regarding profit or loss; there is no trading model or strategy in the market that guarantees absolute profitability.
From a judicial perspective, courts generally exercise a reasonable degree of latitude regarding the performance claims made by forex fund managers; the mere mention of "profitability" does not automatically constitute false advertising. Objectively presenting the results of historical backtesting or accurately disclosing long-term profitability achieved during past live-trading periods is generally considered a compliant form of performance representation. However, if promotional language includes absolute claims or guarantees—such as "guaranteed profits," "sure-fire returns," or "risk-free gains"—it crosses the legal line into false advertising.
For foreign exchange (forex) fund managers offering managed account services, the core of compliant promotion lies in strictly distinguishing between historical performance and future market expectations. A compliant approach involves: demonstrating long-term profitability over a specific historical period based on actual, two-way (long/short) trading experience and a defined trading system; while explicitly refraining from making any definitive promises regarding future profit or loss, given the uncontrollable variables inherent in the forex market. By transparently disclosing the risks of two-way trading and clearly separating past results from future projections, fund managers can effectively manage compliance risks.
In summary, forex fund managers must adhere to the following bottom lines when promoting their performance: strictly avoid making absolute guarantees regarding capital preservation or profits; present historical performance objectively and truthfully; and provide full disclosure of the leverage-related risks and the inherent uncertainty of gains and losses in two-way forex trading. Adhering to these requirements helps avoid being classified as engaging in false advertising.
The forex market is characterized by its two-way (long/short) trading capability, continuous price fluctuations, and the absence of absolute highs or lows; there are no fixed "tops" or "bottoms" in market trends. The primary reason most traders suffer persistent losses is their reliance on subjective market predictions—specifically, the habit of pre-positioning trades or attempting to "pick the bottom" or "call the top"—which runs counter to the objective laws of market movement.
A common pitfall among traders is the tendency toward "counter-trend" (or "left-side") trading: relying on subjective judgment, traders often place long orders during market pullbacks or short orders during rebounds, attempting to secure the most favorable entry price and capture outsized gains from a perceived one-sided trend. Foreign exchange (forex) market movements are characterized by a high degree of both randomness and persistence. The support and resistance levels identified by traders are merely subjective projections rather than reliable signals of a trend reversal; in most cases, they serve only as transitional zones within an ongoing trend. Following a pullback or rebound, the market typically continues its existing directional trend or range-bound oscillation. Attempting to "anticipate" the market by entering positions prematurely—a practice known as "left-side" trading—often leads to persistent unrealized losses and puts the trader in a reactive, disadvantageous position.
Even if a preemptive position happens to coincide with a genuine trend reversal, it is impossible to achieve consistent, long-term profitability this way. The forex market is predominantly range-bound or sideways for long periods, which erodes a trader's patience, ties up margin, and significantly lowers capital efficiency. Furthermore, even if the market eventually breaks out of a range to establish a clear trend, positions taken in anticipation often fail to align with the actual market rhythm, resulting in a scenario where the market moves, yet the positions remain unprofitable.
Ultimately, "left-side" strategies—those based on subjective forecasting—most often end in stop-loss triggers or trapped positions. The key to achieving consistent, long-term profitability in forex lies in "right-side" (trend-following) trading. This requires abandoning subjective speculation, waiting for a clear trend and concrete trading signals before entering the market, avoiding the urge to blindly "bottom-fish" or "top-pick," and instead capturing opportunities based on confirmed market movements.
 13711580480@139.com
 +86 137 1158 0480
 +86 137 1158 0480
 +86 137 1158 0480
z.x.n@139.com
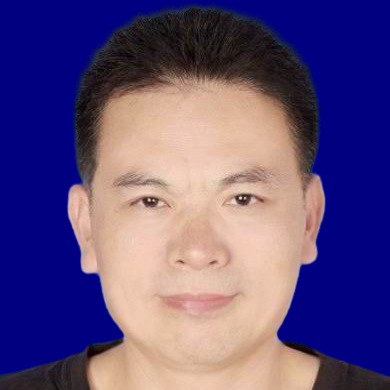 Mr. Z-X-N
 China · Guangzhou

